What Is Insurance? How It Fits Into Your Financial Plan
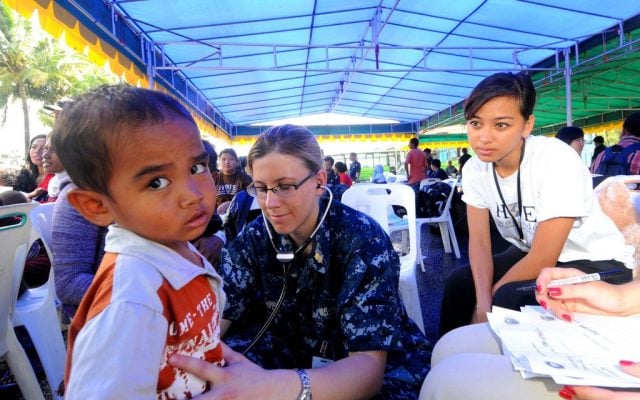
A night of high fever, a frantic rush to the hospital — and the worry over the bill that can shake any parent. When an emergency hits, the question what is insurance is no longer distant theory; it becomes a way for a family to keep its finances steady.
In this article
- 🛡️ What Is Insurance? The Simple Principle Behind It
- 🧩 Why Insurance Is a Key Piece of the Financial Plan
- 💡 Is Insurance an Expense or an Investment for the Family?
- 📒 Common Types of Family Insurance
- 🌱 When Should a Family Start Thinking About Insurance?
- ✅ Checklist: Choosing the Right Insurance for Your Family
- 🔍 Before You Sign, Read These Carefully
- 🤝 Protecting Your Family Is a Journey, Not a One-Time Decision
🛡️ What Is Insurance? The Simple Principle Behind It
Insurance is a risk-transfer tool. A family pays a regular premium to an insurer; in return, when a covered event occurs, the insurer provides financial support according to the agreed terms.
Put simply, insurance is like a cushion placed between a family and unexpected financial shocks. Instead of bearing the full cost alone, the family shares the risk on a community principle.
Keep in mind that not every event is covered. Each contract has its own scope of coverage, conditions and exclusions, so reading the terms carefully is a step you cannot skip.
🧩 Why Insurance Is a Key Piece of the Financial Plan
A family financial plan usually has three layers: accumulation, growth and protection. If an emergency fund helps with smaller costs, insurance is the protective layer for major risks that savings may not fully cover.
A long course of treatment, an accident or property damage can drain years of savings. Insurance helps reduce the financial impact, so long-term goals such as a child’s education or retirement are not interrupted.
For foreigners living in Vietnam, insurance is also a way to access medical and healthcare services proactively. You can read more about financial planning for expats in Vietnam to see more clearly where insurance sits within your overall personal finances.
💡 Is Insurance an Expense or an Investment for the Family?
This is a very common question. In essence, the insurance premium is a cost paid for financial security — much like paying for a promise of support when a risk occurs.
Insurance should not be seen as a channel for profit, nor should you expect “interest” from it. Its real value lies in stability: the family knows that if something happens, there is a support mechanism in place according to the contract’s commitments.
Balance is what matters. The premium should fit within the family budget without affecting essential daily needs. If you are unsure how to allocate, review your income and expenses first before deciding.
📒 Common Types of Family Insurance
| Type of insurance | General role | Who it suits |
|---|---|---|
| Health insurance | Supports medical examination and treatment costs according to the terms | The whole family, especially young children and older adults |
| Accident insurance | Support when an accidental injury occurs | People who travel and work outside the home frequently |
| Life insurance | Financial protection for dependents when the breadwinner is no longer there | Families with dependents |
| Property and vehicle insurance | Compensates property damage according to the contract | Homeowners and car owners |
To understand the classification more deeply, you can read this comparison of non-life insurance vs. life insurance to choose the right product group for your needs.
🌱 When Should a Family Start Thinking About Insurance?
There is no single answer for everyone. However, certain moments often prompt families to rethink their protection needs: when a baby arrives, when there is a new dependent, when buying a house or car, when income changes, or when work carries more risk.
These are also good times to review existing policies, because insurance needs change over the life cycle. A contract that fit well a few years ago may no longer reflect the family’s reality today.
✅ Checklist: Choosing the Right Insurance for Your Family
- ☐ Identify the biggest risks your family faces (health, accidents, property)
- ☐ Estimate the financial impact if the risk occurs
- ☐ Match the coverage to the actual needs of each family member
- ☐ Check the exclusions and the conditions for receiving benefits
- ☐ Ask clearly about waiting periods (if any) before benefits take effect
- ☐ Compare the premium with the family’s long-term ability to pay
- ☐ Keep the contract, documents and the insurer’s contact details
🔍 Before You Sign, Read These Carefully
An insurance contract is a legal document, and its terms decide your benefits. Before signing, take time for these questions:
- Which events are covered, and which are not?
- How are benefits paid: reimbursement, direct payment, or a lump sum?
- Are there any limits on medical facilities, region or time?
- What are the procedures for reporting an incident and the documents required for a claim?
If any term is unclear, do not hesitate to ask the advisor or the insurer’s hotline. Specific benefits, payout levels and applicable conditions are always governed by the contract, not by reference articles.
🤝 Protecting Your Family Is a Journey, Not a One-Time Decision
Insurance does not change your life — it helps your life not change too much when the unexpected happens. That is why many families see insurance as a piece that works alongside day-to-day money management.
Start by listing the risks your family faces, then talk to the insurer or an advisor to understand the terms before deciding. A suitable contract, read carefully and understood correctly, is a gift of peace of mind for the people you love.